
Insights
Rule 9B and the Foreign Shareholder
Why Dematerialisation Has Become a Cross-Border Deal Risk
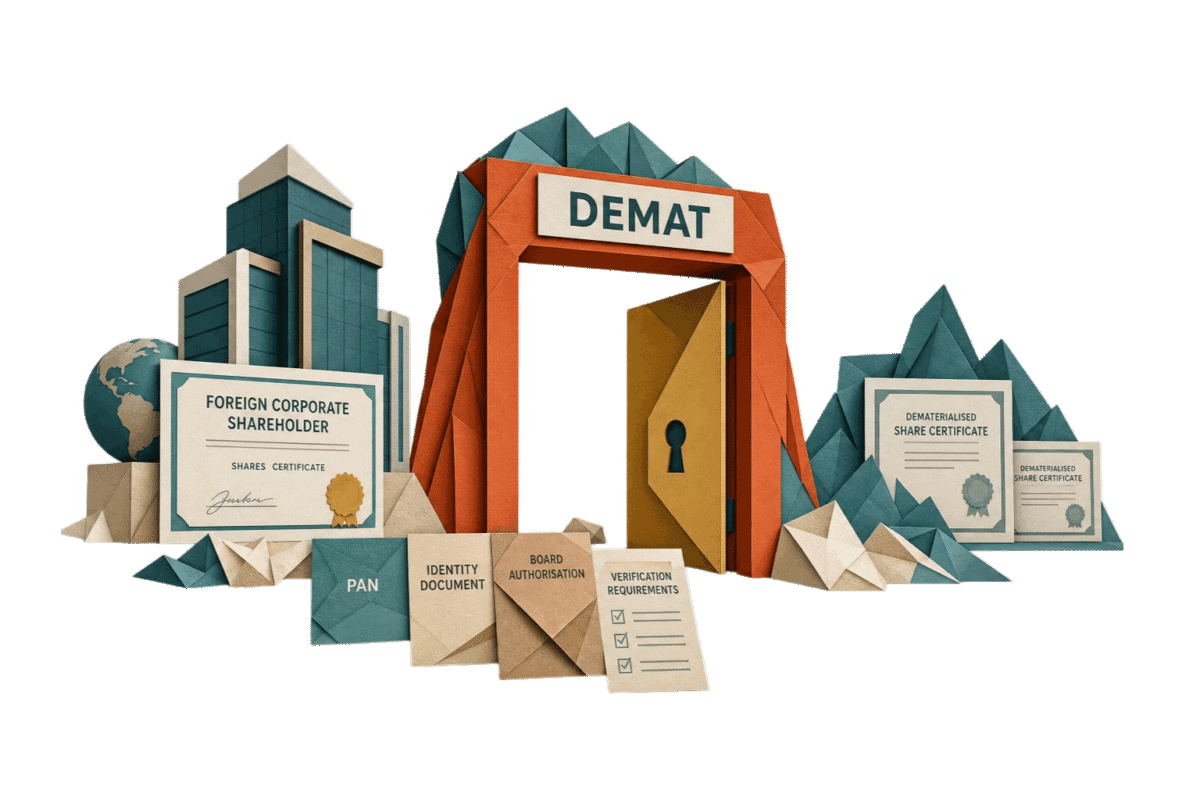
I. Obligation
Rule 9B of the Companies (Prospectus and Allotment of Securities) Rules, 2014 imposes two distinct duties. It requires the company to amend its articles, appoint a registrar and share transfer agent, and secure an ISIN,work that is entirely domestic and can be completed in weeks. It separately requires the holder to dematerialise its own shares before transferring or subscribing further. That second duty assumes a domestic holder: someone with a PAN, Indian-issued identity documents, and a depository participant who has already verified them. Where the holder is a foreign parent that invested through the FDI route and has no other footprint in the Indian financial system, none of those assumptions holds. This is not a marginal case. A private subsidiary cannot claim the small-company exemption regardless of size, so the structure most likely to carry foreign ownership is also the one least able to escape Rule 9B.
II. Enforcement
Until recently, non-compliance carried commercial rather than punitive consequences: a company that had not dematerialised simply could not allot, buy back, or register a transfer. That changed in August 2026, when the Registrar of Companies, Bangalore, adjudicated against a company whose board approved a transfer without confirming the transferor’s shares were dematerialised. The penalty, under Section 450 of the Companies Act, 2013, was modest — but the order matters for two reasons. First, it shows breaches are now caught at the level of a single transaction, not just a company’s overall failure to obtain an ISIN, so exposure attaches at completion, in the very document parties are signing. Second, the order left open whether the underlying transfer is valid. Commentary on the NCLT Mumbai bench’s 2023 decision in Amrex Marketing v. Harinagar Sugar Mills is split. Some read breaching transfers as void, others as protecting the shareholder’s statutory right to transfer despite the company’s own failure. A buyer from an offshore seller therefore faces an unpriced risk: the fine is survivable, but a void transfer in the chain of title is not.
III. The Chokepoints
Four sequential, individually reasonable gates compound into months of delay. First, a demat account requires a PAN, which a foreign body corporate obtains via Form 49AA with an apostilled certificate of incorporation, using a tax identifier purely as an access key, since no Indian income is involved. Second, Indian onboarding checklists assume a board resolution and signatory list, but foreign entities often govern differently (member consents for an LLC, a register extract for a Dutch or German entity, a trust deed for a trustee). With no published equivalence table, operations teams ask for a document that simply does not exist in the applicant’s jurisdiction. Third, depository participants bear the regulatory risk of onboarding errors under AML/CFT rules while the foreign shareholder bears only the delay. So, participants rationally over-document, requesting more information in tranches. Fourth, officers are asked for passports and personal details that foreign counsel will not release without a stated purpose and legal basis, and India’s new data protection statute offers no published protocol resolving that impasse.
IV. The Asymmetry
India has, in parallel, been actively easing the equivalent journey for individuals: SEBI relaxed NRI re-KYC geo-tagging in December 2025, the FY2026-27 Budget widened the Portfolio Investment Scheme to non-resident individuals, the Non-Debt Instruments Rules were amended in June 2026, and an August 2026 SEBI consultation paper proposes fully digital onboarding, e-signatures, video verification, and portability of KYC across intermediaries for individual non-residents from FATF-compliant jurisdictions. None of this extends to foreign corporate shareholders, even though two of the four proposals, portability and reliance on KYC already performed by a regulated institution abroad, are structural, not technological, and have nothing to do with the client being a natural person. A parent that has cleared institutional KYC with a bank in Frankfurt or Singapore is still asked to start from zero at an Indian counter.
V. Diagnosis and Fixes
No single regulator owns this problem. The MCA sets and sanctions the obligation but has no hold over depository participants. SEBI supervises participants but they breach nothing by being slow; the CBDT controls the PAN with no stake in a company-law deadline. RBI/FEMA are indifferent to share form. The Indian company is penalised despite having no leverage over any of these actors. Rule 9A’s model, built in 2018 for unlisted public companies with largely domestic, already-onboarded shareholders, was extended to private companies without building the infrastructure their offshore-heavy registers require.
Most fixes are administrative, not legislative:
- One exhaustive, published documentation checklist for non-individual foreign holders, binding on participants once satisfied.
- A published equivalence table mapping Indian expectations to foreign-entity analogues (LLC consents, register extracts, trust/partnership resolutions).
- A service clock — queries raised in one tranche within a set period, a named escalation officer, and a depository-level escalation route.
- Extending SEBI’s portability and third-party-reliance proposals to entities, not just individuals.
- Explicit recognition of the Hague electronic apostille programme, replacing counter-level judgment calls with a lookup.
- Decoupling or fast-tracking the PAN requirement — a depository-level identifier, or a priority lane triggered by an allotted ISIN.
Failing all of this, a defined extension for foreign corporate holders, mirroring the horizon already given to producer companies, would apply the same logic.
VI. Practice
Transaction teams cannot wait for the fix. Practical steps could include starting the PAN application at term-sheet stage, since it is the longest pole, treating demat readiness as its own condition precedent with a long-stop date, diligence regarding the target’s ISIN and PAS-6 filing history before pricing, choose a depository participant experienced with foreign entities and get its full document list in writing upfront, obtain one omnibus board authorisation from the foreign parent, agree on the data-protection position with the parent’s counsel at the outset and where the seller is offshore, confirm dematerialisation before the board approves the transfer. It is important to note here that liability attaches to the resolution, not the closing payment.
The compliance date has passed and adjudication orders have begun. Until the regulatory gap closes, its cost is being borne by the parties least able to close it themselves.